What Information Insurance Companies Require After Roadside Towing
Introduction
A vehicle breakdown or accident can leave you dealing with several problems at once. You may need to arrange a tow truck, find a safe place to leave your vehicle, contact your insurance company, and figure out how the damage will be handled. Once your vehicle has been towed, the paperwork can feel like another complication, especially if you have never filed an insurance claim before.
Knowing what information insurance companies require after roadside towing can make the process easier. Insurers may ask for the towing receipt, pickup and drop-off locations, photographs, incident details, and information about the company that performed the tow. The exact requirements depend on your policy, the reason for the tow, and whether you are filing an accident claim or requesting roadside assistance reimbursement.
Keeping these records organized can help you explain what happened, document the services you received, and avoid unnecessary delays caused by missing information. Drivers in Marrero, Harvey, Gretna, Westwego, and surrounding Louisiana communities can benefit from preparing these details immediately after a roadside emergency.
Why Insurance Companies Request Information After Towing
Insurance companies need to understand why your vehicle was towed, what services were provided, and whether the expense qualifies for coverage under your policy. A towing receipt alone may not answer every question, particularly when the tow follows a collision or mechanical breakdown.
The documentation also helps the insurer determine how the towing expense relates to the incident and whether additional expenses, such as storage fees, require review.
To Verify the Reason for Towing
The first question an insurance adjuster may ask is why your vehicle needed a tow. A car that cannot move after a collision presents different claim considerations from one that has a dead battery or a failed transmission.
Common reasons for roadside towing include:
Vehicle damage following a traffic accident.
Engine overheating or mechanical failure.
A flat tire that cannot be safely repaired roadside.
A dead battery or electrical problem that prevents the vehicle from starting.
A vehicle stuck in mud, a ditch, or another difficult location.
A breakdown that makes driving unsafe.
Explain the situation accurately. If you do not know what caused the problem, describe the symptoms rather than guessing at a mechanical diagnosis.
To Determine Whether the Expense Is Covered
Not every towing expense is covered by every auto insurance policy. Some policies include roadside assistance, while others offer it as an optional add-on. Collision coverage or comprehensive coverage may also apply to certain towing expenses associated with a covered loss, depending on the policy terms.
An insurer may ask for documentation to determine whether the tow qualifies under the applicable coverage. For example, a driver whose car is damaged in a covered collision may have different benefits available from a driver whose vehicle simply stops running because of an unrelated mechanical failure.
Always check your policy or contact your insurer before assuming reimbursement is guaranteed.
What Information Should You Collect After Roadside Towing?
The most useful approach is to gather your towing records, incident details, and insurance information in one place. Collect what you can safely obtain at the scene, then request any missing documents from the towing provider.
1. Towing Receipt or Invoice
The towing receipt is usually one of the most important documents for a reimbursement request. It records the service performed and the amount charged.
A detailed invoice should ideally include:
Towing company's name and contact information.
Date and time of service.
Vehicle description.
Pickup location and destination.
Type of towing or roadside assistance provided.
Itemized charges and the total amount paid.
Payment status and payment method, when applicable.
Invoice or transaction number.
Depending on the circumstances, the invoice may also list mileage, winching, after-hours service, roadside labor, or other applicable fees.
Practical tip: Keep the original receipt and save a digital copy. If the invoice only says "tow service" without describing the route or service provided, ask the company whether it can supply a more detailed version.
2. Date, Time, and Location of the Incident
Insurance companies often need to establish when and where the breakdown or accident occurred. These details help connect the towing service to the event described in your claim.
Record the date, approximate time, road name, nearby intersection, business, or recognizable landmark. If your vehicle was collected from a highway shoulder in Harvey and transported to a repair shop in Marrero, document both locations.
If the tow occurred hours after the original incident, explain the timeline. For example, you may have arranged roadside assistance immediately but needed a second tow after the initial destination could not accept the vehicle.
Clear location records are particularly helpful when the vehicle has been moved more than once.
3. Vehicle Information
Your insurer will need enough information to identify the vehicle involved in the claim. Keep these details available:
Vehicle identification number (VIN).
Make, model, and model year.
License plate number and state of registration.
Current mileage, if available.
Registered owner's name.
Insurance policy number.
The VIN can usually be found on the driver's side dashboard near the windshield or on the vehicle registration documents. If the vehicle is inaccessible after an accident, use your registration or insurance records rather than putting yourself at risk to retrieve information.
Confirm that the vehicle details on the towing invoice match the vehicle listed on your insurance policy.
4. Photographs of Vehicle Damage and the Scene
Photographs can help establish the vehicle's condition before repairs begin. They are especially useful when towing follows a collision, road hazard, or vehicle recovery incident.
If it is safe to do so, photograph:
Visible damage from several angles.
The overall condition of the vehicle.
Flat tires, broken wheels, or other visible mechanical problems.
Debris or road hazards relevant to the incident.
The vehicle's original location.
The vehicle after it reaches a repair facility, if its condition has changed during transport.
Take pictures from a safe location without standing in traffic or approaching an unstable vehicle. Never delay emergency assistance to obtain photographs.
Photos do not automatically establish who was responsible for an accident, and they may not prove the underlying cause of a mechanical failure. They are supporting evidence that can be considered alongside other claim records.
5. Police or Accident Report, When Applicable
If towing followed a traffic collision, your insurer may ask whether police responded and whether an incident report is available. The insurer may also request the report number or a copy of the report.
Provide the information you have, even if the final report has not yet been issued. Ask your insurer how to submit it later.
A police report is not required for every breakdown or towing service. A dead battery, for example, generally does not create the same reporting needs as a collision involving injuries, property damage, or other circumstances that warrant law enforcement involvement.
Follow applicable reporting requirements and cooperate with the relevant authorities.
6. Details of the Towing Company
Your insurance company may need to verify who performed the tow. The provider's name, phone number, invoice, and business details can help the insurer confirm the service.
Keep any dispatch confirmation, text message, email, work order, or payment confirmation you received when arranging roadside assistance.
If your insurer dispatched the towing company directly, note the assistance reference number and the name of the service provider. You may not need to submit a separate reimbursement claim for a service already arranged and paid for through your coverage, but you should still retain any records provided to you.
What Additional Documents Are Needed for Different Types of Towing?
The documentation required after a tow depends largely on what happened to the vehicle. Understanding the difference between roadside assistance, accident towing, and vehicle recovery helps you prepare the right records.
Roadside Assistance Towing After a Breakdown
If your vehicle stops running because of a dead battery, engine problem, overheating, or another mechanical issue, your insurer may request:
A towing invoice showing the service and charge.
Your policy or roadside assistance membership details.
The pickup and drop-off locations.
A brief explanation of why the vehicle could not be driven.
Any service authorization or reference number.
Some roadside assistance plans have limits on towing distance, eligible destinations, service frequency, or covered expenses. Review those conditions before requesting reimbursement.
If a mechanic later identifies the cause of the breakdown, keep the diagnostic report and repair invoice. These documents may help explain the incident, although routine mechanical repairs are generally treated differently from accident damage.
Towing After a Car Accident
Accident-related towing usually requires more supporting documentation because the insurer may be investigating vehicle damage, liability, and the cost of repairs.
In addition to the towing invoice, keep any relevant police report, photographs, other driver's contact and insurance information, witness details, and claim number. Provide the date and location of the collision and explain where the vehicle was taken.
If the vehicle is not drivable, ask the insurer where it should be transported. Moving a damaged vehicle to an appropriate repair facility or inspection location can help coordinate the claim, but follow the insurer's instructions where practical.
If you are concerned about accumulating storage charges, notify your adjuster promptly and ask about an approved destination or transfer procedure.
Flatbed Towing and Vehicle Recovery
Flatbed towing may be used for vehicles with significant damage, certain drivetrain concerns, low ground clearance, or other transport requirements. Vehicle recovery may involve additional work to retrieve a vehicle from mud, a ditch, or another difficult position.
The invoice should describe the actual service performed. Depending on the job, relevant details may include flatbed transport, winching, recovery labor, mileage, and additional equipment charges.
An insurer may request an explanation of why the selected method was necessary. For example, a vehicle with collision damage affecting its wheels may require a different loading procedure from a car that can be safely driven onto a flatbed.
Do not assume that every recovery or specialized towing charge is covered. Ask the insurer whether the expense qualifies under the applicable policy and whether additional authorization is needed.
How to File an Insurance Claim for Towing Expenses
Submitting the correct records promptly can make a towing reimbursement request easier to review. The following steps provide a practical process.
Step 1: Review Your Insurance Coverage
Check your declarations page, roadside assistance endorsement, or policy documents. Look for information about towing, labor, mileage limits, deductibles, reimbursement rules, and any restrictions on service providers.
If you cannot find the relevant terms, contact your insurer and ask which coverage applies to your situation.
Step 2: Notify Your Insurance Company
Report the incident using the insurer's claims phone number, mobile app, or online claim portal. Explain whether the tow followed an accident, a breakdown, or another roadside emergency.
If an accident claim already exists, provide the existing claim number rather than assuming you need to open another one.
Step 3: Ask What Documents Are Required
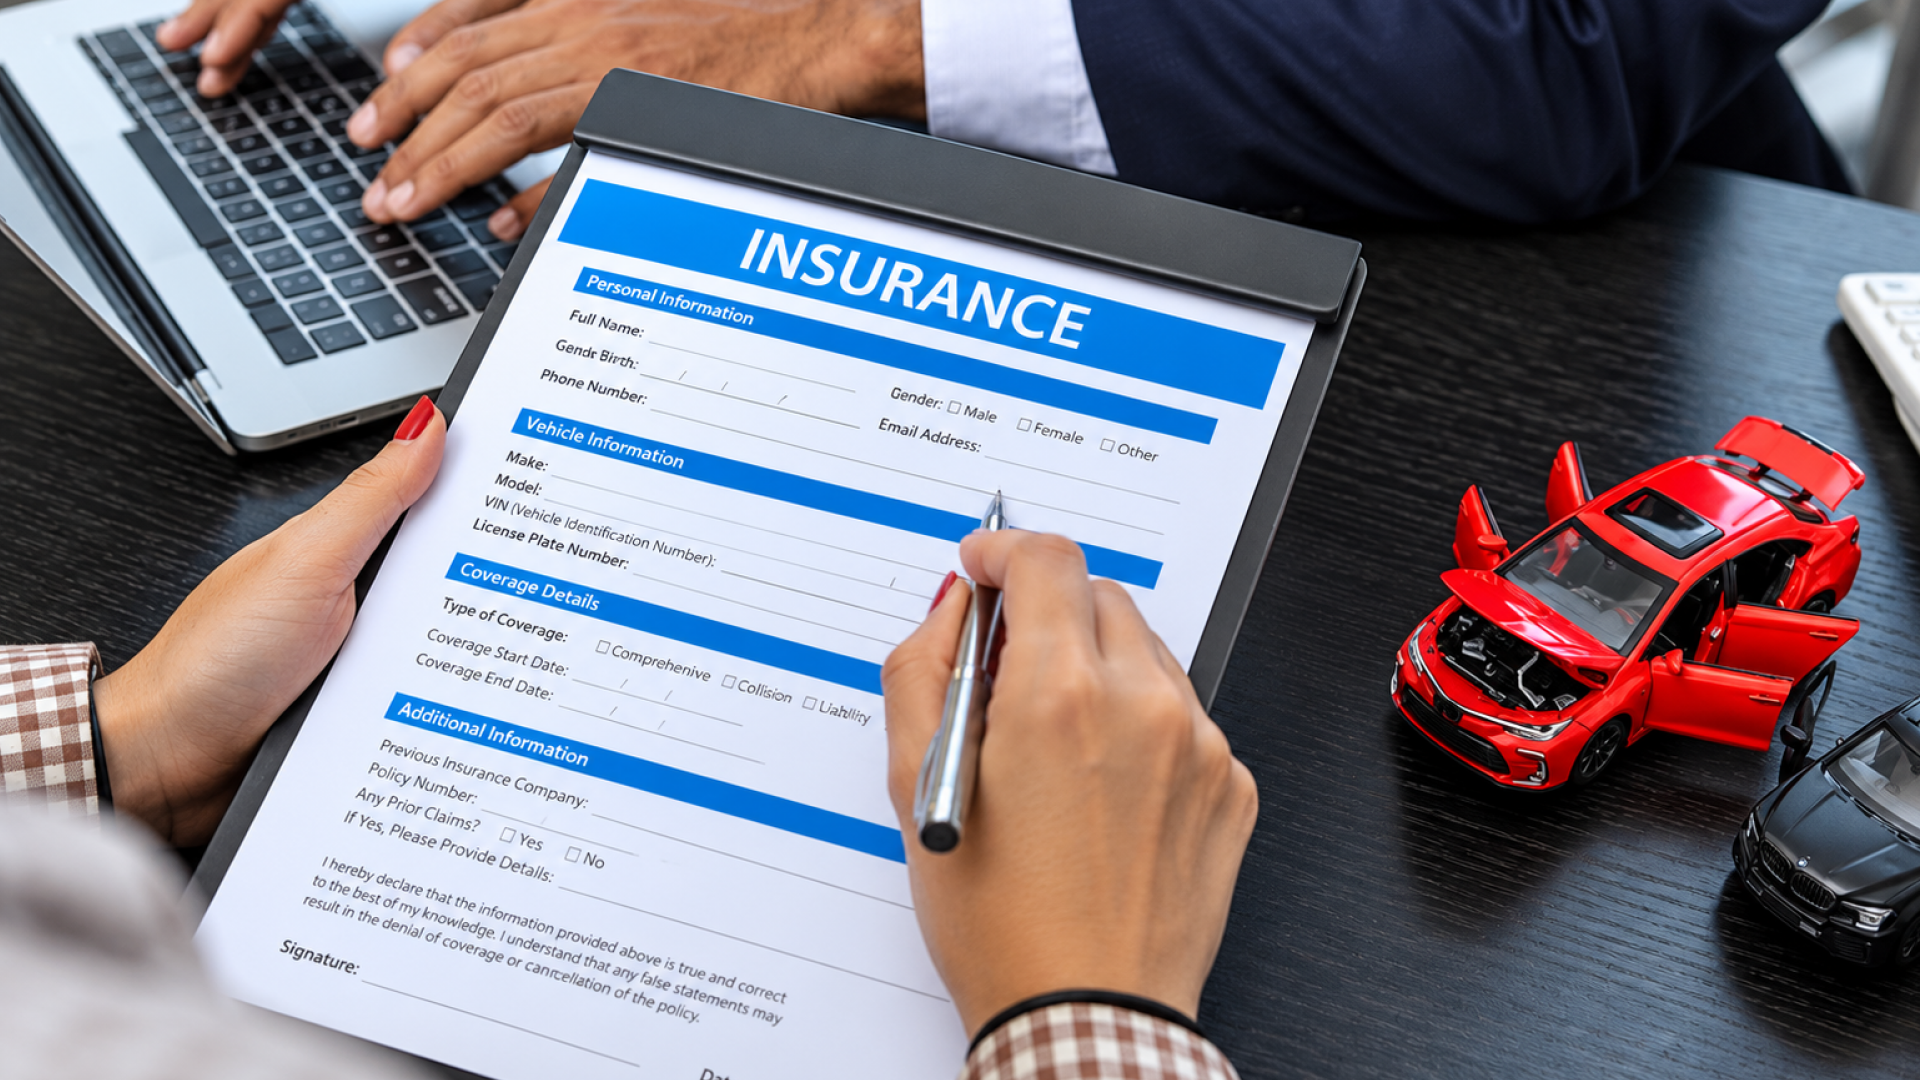
Before submitting the claim, ask whether the insurer needs an itemized invoice, proof of payment, photographs, an incident report, repair documentation, or a specific reimbursement form.
Also ask about submission deadlines and whether the company requires original documents or accepts digital copies.
Step 4: Submit the Documents Together
Organize your records in a logical order:
Claim number and policyholder information.
Towing invoice and proof of payment.
Incident date, time, and location.
Vehicle information and relevant photographs.
Police report or other supporting records, if applicable.
Repair estimates, diagnostic reports, or additional invoices when requested.
Use clear file names and check that every image or document is readable before uploading it.
Step 5: Keep Track of the Claim
Save the submission confirmation, note the date you sent the documents, and record the name of the representative you spoke with when possible.
If the insurer asks for additional information, respond promptly and retain copies of your response. If reimbursement is denied, request an explanation identifying the relevant policy provision or missing requirement.
You can then determine whether the issue involves an excluded expense, a coverage limit, incomplete documentation, or a decision that merits further review.
Common Mistakes That Can Delay Towing Reimbursement
Small documentation gaps can lead to follow-up questions or prevent an insurer from confirming an expense. Avoid these common mistakes whenever possible.
Losing the Receipt or Submitting an Incomplete Invoice
A bank transaction may show that you paid a towing company, but it may not identify the service, mileage, or destination. Ask for a duplicate invoice if the original is lost.
Assuming Every Tow Is Covered
Roadside assistance, collision coverage, comprehensive coverage, and mechanical breakdown expenses are not interchangeable. Confirm which policy provision applies instead of relying on a general assumption about towing benefits.
Failing to Document Additional Charges
Winching, storage, extended mileage, or a second tow can increase the total expense. Keep separate invoices and explanations for each service so the insurer can understand what was charged and why.
Waiting Too Long to Address Storage Fees
A vehicle held at a towing yard or storage facility may incur additional charges. Contact your insurer promptly to discuss the next step, and ask the facility about its current charges and payment requirements.
Do not assume that insurance will cover every day of storage or that the insurer will automatically arrange vehicle release.
Giving Inconsistent Information
The incident description, towing invoice, and claim report should accurately reflect the same event. If you discover an error, correct it and explain the discrepancy rather than leaving conflicting information unexplained.
What If Your Insurance Company Denies Towing Reimbursement?
A denied towing claim does not always mean the matter is settled, but the next step depends on the reason for denial.
Start by asking for the decision in writing. Review whether the denial refers to an exclusion, an exhausted roadside assistance benefit, an expense exceeding a coverage limit, a lack of prior authorization, or insufficient documentation.
If the issue is missing paperwork, ask whether you can submit the additional records. If the insurer says the expense is excluded, review the policy language and request clarification if the explanation is unclear.
Keep a record of calls, emails, invoices, and claim decisions. If you believe the decision conflicts with your policy, use the insurer's formal review or complaint process. Louisiana policyholders may also contact the Louisiana Department of Insurance for information about insurance complaints and consumer assistance.
Avoid assuming that a reimbursement dispute automatically establishes bad faith or guarantees payment. The applicable policy language and circumstances determine what options are available.
Best Practices for Keeping Towing Records Organized
Preparing a simple roadside documentation folder can save time when you need to submit a claim. You do not need complicated software; a secure folder on your phone or computer is often enough.
Create a Digital Record Immediately
Save the towing receipt, payment confirmation, photographs, and any dispatch messages as soon as practical. Give each file a descriptive name, such as the incident date followed by the document type.
Keep a backup in a secure location and avoid sharing sensitive policy information through unverified links or unfamiliar contacts.
Confirm the Destination Before the Tow
If your insurer has specific requirements for where the vehicle should go, confirm them before transport whenever circumstances allow. A repair shop, dealership, home address, and storage yard may have different costs and implications for your claim.
If immediate safety requires an emergency tow, prioritize safety first and contact the insurer as soon as possible afterward.
Ask Questions Before Authorizing Extra Services
Before approving non-emergency additional services, ask for an explanation of the charges and whether they are separate from the original towing fee. If the vehicle needs recovery or specialized transport, request an itemized estimate when practical.
An estimate does not guarantee insurance reimbursement, but understanding the expected charges can help you make an informed decision.
Conclusion
Insurance companies generally need enough information to verify why your vehicle was towed, what service was performed, how much it cost, and whether the expense falls within your coverage. A detailed towing invoice, accurate incident information, vehicle details, photographs, proof of payment, and relevant accident records provide a useful starting point.
The documents required after roadside towing vary by policy and circumstances. A routine breakdown may involve a straightforward roadside assistance reimbursement request, while accident towing or vehicle recovery may require additional records and coordination with an adjuster.
For drivers in Marrero, Harvey, Gretna, Westwego, and nearby Louisiana communities, the best approach is to save every towing record, ask the insurer about coverage and submission requirements, and address storage or destination concerns promptly. Organized documentation cannot guarantee payment, but it gives your insurance company a clearer picture of what happened and helps you respond efficiently if further information is needed.
Frequently Asked Questions
1. What documents do I need to claim towing expenses from insurance?
You may need an itemized towing invoice, proof of payment, your policy or claim number, the incident date and location, and vehicle details. Accident-related claims may also require photographs, a police report, or repair documentation. Requirements vary by insurer and coverage.
2. Does car insurance automatically cover towing after a breakdown?
No. Towing after a mechanical breakdown is commonly covered only when the policy includes applicable roadside assistance or another relevant benefit. Review your policy for mileage limits, service restrictions, and reimbursement conditions before assuming the expense will be paid.
3. Can I get reimbursed if I paid the towing company myself?
Possibly. Some insurance policies allow reimbursement for eligible towing services paid out of pocket. Keep the detailed invoice and proof of payment, then ask your insurer whether the service qualifies and whether you must complete a reimbursement form.
4. What should a towing receipt include for an insurance claim?
A useful towing receipt includes the provider's name and contact information, service date, vehicle identification, pickup and drop-off locations, type of service, itemized charges, and total cost. Proof of payment and an invoice number can also help support the claim.
5. Do I need a police report to claim towing expenses?
Not always. A routine breakdown or dead battery generally does not require a police report solely for towing reimbursement. If the tow follows a collision, your insurer may request a report or report number, depending on the circumstances and claim requirements.
6. Will insurance pay for flatbed towing after an accident?
Flatbed towing may qualify for coverage when it is connected to a covered accident, but payment depends on your policy, the circumstances, and applicable limits. Keep an itemized invoice explaining the service and ask your adjuster whether the charge is eligible.
7. Does insurance cover towing and vehicle storage fees?
Some policies cover eligible towing expenses after a covered incident, but storage fees may be subject to separate conditions or limits. Contact your insurer promptly about the vehicle's location, approved destination, and any accumulating storage charges.
8. How long does towing reimbursement take?
There is no universal reimbursement timeline. Processing depends on the insurer, policy requirements, claim complexity, and whether the submitted documents are complete. Ask your insurance company for its expected timeline and respond quickly to requests for additional information.
9. What if I lost my towing receipt?
Contact the towing company and request a duplicate invoice showing the service, date, locations, and charges. If available, retain your payment confirmation and dispatch messages as supporting records. Ask your insurer whether it accepts these documents if a complete invoice cannot be obtained.
10. Can an insurance company deny a towing reimbursement claim?
Yes. An insurer may deny reimbursement if the expense is excluded, exceeds a coverage limit, fails to meet policy conditions, or lacks sufficient documentation. Request the reason in writing, review the policy, and ask whether additional records or a formal review could address the issue.